What Happens to Your BVG Pension When You Quit Your Swiss Job?
The transition from being a gainfully employed resident to someone "between jobs" or "leaving for good" in Switzerland is often met with a mountain of paperwork that feels designed to confuse. I still remember the pit in my stomach when I received my first "exit statement" from my Zurich employer's pension fund; I had no idea what a vested benefit was or why my money was being moved to a holding account I hadn't authorized. This guide settles the confusion by explaining exactly what happens to your BVG pension when you resign and how to ensure your hard-earned Swiss francs don't end up lost in the federal archives.
Understanding the BVG Transition from Employer Fund to Vested Benefits
In the Swiss 2nd Pillar system, your pension is tied directly to your current employer’s specific pension fund (Pensionskasse). The moment you officially stop working for that company, you are no longer a member of their collective insurance pool. This triggers a process where your accumulated capital—consisting of your contributions, your employer's matching contributions, and the interest earned—must be "vested" and moved out. This capital is officially known as your Austrittsleistung or "termination benefit."
The Concept of the Vested Benefit
Think of your vested benefit as a portable suitcase of cash that belongs to you, but with heavy strings attached by the Swiss government. While you are working, your Understanding Swiss Payslips: Deductions for AHV, ALV, and NBU shows exactly how much is being deducted each month, but you only see the full scale of this "suitcase" when you quit. Your former employer's pension fund is legally required to transfer this entire amount out of their system. They cannot keep it, and except in very specific circumstances, they cannot pay it directly into your personal bank account.
The amount is calculated based on your total savings plus the legal minimum interest rate set by the Federal Council. It is vital to request a final statement of your benefits to ensure every year of service was correctly calculated. If you have been in Switzerland for a long time, this sum is likely one of your most significant financial assets. Understanding The Three-Pillar Pension System: AHV, BVG, and Private Savings is the first step in realizing that the 2nd pillar is often much larger than the state pension (1st pillar) for most expats.
The Automatic Transfer and the 90 Day Trap
If you do not provide your former employer with instructions on where to send your pension money within a certain timeframe—usually 90 days—they won't just hold onto it for you. By law, they must transfer it to the "Substitute Occupational Benefit Institution" (Stiftung Auffangeinrichtung BVG). This is a federal "catch-all" foundation. While your money is safe there, it typically earns the absolute minimum legal interest rate and is invested very conservatively.
I have met dozens of expats who left Switzerland years ago, only to realize later that they had thousands of francs sitting in the Substitute Institution, losing value against inflation. To avoid this, you must proactively manage the destination of these funds. You should look into Freizügigkeitskonto: Managing Vested Pension Benefits Between Jobs to understand how to maintain control over these assets during your transition.
Choosing Your Own Vested Benefits Foundation
You are not obligated to use the default state option. Many modern expats choose to open a private Vested Benefits Account (Freizügigkeitskonto) with a bank or a dedicated fintech provider. These providers often offer much better digital interfaces and, more importantly, the ability to invest a portion of the funds into the stock market.
If you are a savvy investor who uses platforms like Trade Republic for your private brokerage, you might find the low-interest rates of a standard vested benefits savings account frustrating. In that case, you might investigate whether your provider allows for higher equity exposure. Just remember that because this is a pension, there are strict limits on how much risk you can take. If you find yourself with multiple small pots of money from different short-term contracts, you should follow the steps on How to Consolidate Multiple Vested Benefit Accounts into One to save on administrative fees and simplify your future payout.
Your Three Main Paths After Handing in Your Notice
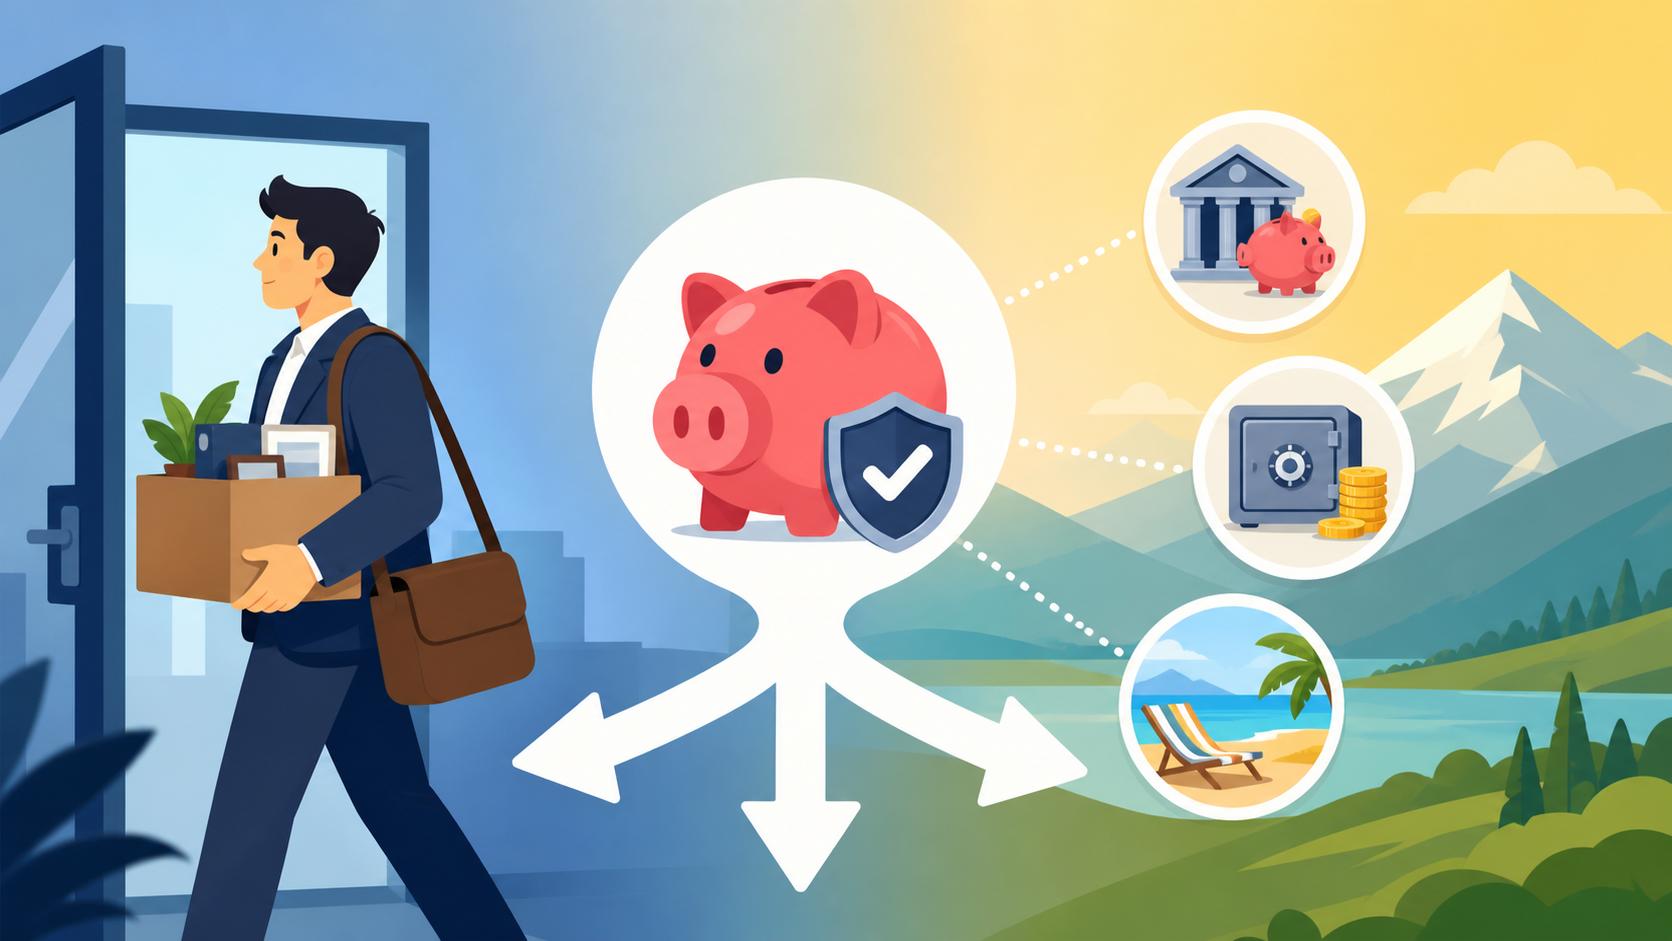
The destination of your BVG money depends entirely on what your next move is. Switzerland is a country of rules, and the "pathway" for your pension is strictly dictated by your employment status on the first day after your notice period ends.
Scenario A: Moving Directly to a New Swiss Employer
This is the simplest path. If you are quitting Job A to start Job B on the first of the following month, your money simply moves from Pension Fund A to Pension Fund B. You will receive a document from your new employer's pension fund with their bank details (the "payment slip" for the pension transfer). You hand this to your old HR department, and the money is wired across.
In this scenario, you cannot keep the money in a private vested benefits account. The law requires that the full amount of your termination benefit be transferred to your new employer’s fund to ensure you are fully covered for risks like disability and death. When you start the new role, pay close attention to your new Pillar 2 (BVG): Understanding Your Swiss Occupational Pension statement. Sometimes, if your new salary is higher, you might even have the option to "buy into" the new fund to increase your future retirement income.
Scenario B: Taking a Career Break or a Sabbatical
If you are taking six months off to travel or are simply taking your time to find the right next role, your pension money enters a state of "hibernation." Since there is no new employer fund to receive the money, you must open a Vested Benefits Account. You can open up to two accounts at two different foundations.
During this period, you should be mindful of the interest rates. Many expats find that leaving their money in a big-box Swiss bank results in almost zero growth. This is where you might consider providers that offer investment-linked accounts. If you are looking to grow your wealth while traveling, you might be using Wise to manage your daily currency needs, but for your BVG, you need a Swiss-regulated foundation. If you are curious about maximizing returns, read about Can You Invest Your Vested Benefits (Freizügigkeit) in the Stock Market? to see if an equity-heavy strategy fits your risk profile during your career break.
Scenario C: Becoming Self-Employed or Starting a Business
Quitting a corporate job to launch your own "Einzelfirma" or "GmbH" is a major milestone. In Switzerland, becoming self-employed is one of the few legal "loopholes" that allows you to withdraw your 2nd pillar pension in cash. This is intended to provide startup capital for your new venture.
However, this is not an automatic right. You must prove your self-employment to the pension fund by providing a confirmation from the social security office (AHV/SVA) that you are registered as an independent. Before you rush to cash out, read Becoming a Sole Proprietor (Einzelfirma): Risks and Registration Steps carefully. Using your pension as startup capital is risky; if the business fails, your retirement "safety net" is gone. Some entrepreneurs choose to only withdraw the "extra-mandatory" portion and keep the mandatory minimum in a vested benefits account for safety.
Leaving Switzerland for Good: The Cash-Out Reality Check
For many expats, quitting a job is the final act before moving to another country. This is where the rules get incredibly complex, and where I've seen the most frustration. You cannot simply "take the money and run" in every situation.
The EU/EFTA Restriction: The Mandatory vs. Extra-Mandatory Split
If you are moving to an EU or EFTA country (like Germany, France, or Italy) and you will be subject to the social security system in that country, you are legally barred from withdrawing the "mandatory" portion of your BVG in cash. The Swiss government wants to ensure this money is saved for your retirement, regardless of where you live in Europe.
In this case, the "mandatory" part must stay in a Swiss Vested Benefits Account until you reach retirement age. However, you can still withdraw the "extra-mandatory" part—the portion of your savings that exceeds the legal minimum requirements. If you are moving to a country outside the EU, such as the USA, Australia, or Japan, the rules are much more relaxed, and you can generally cash out the entire amount. For a deeper dive into these nuances, check out Withdrawing Pillar 2 When Moving to an EU Country: Rules and Restrictions and Cashing Out Pillar 2 Completely When Moving to a Non-EU Country.
Tax Implications of a Pension Payout
If you are eligible for a cash-out because you are leaving Switzerland, the money is subject to a "withholding tax" (Quellensteuer) at the moment of payout. Here is the veteran tip: the tax rate is not based on where you lived in Switzerland, but on the location (canton) of the vested benefits foundation.
If your money is sitting in a Zurich-based bank, you will pay Zurich tax rates. If you move your money to a foundation based in Canton Schwyz before you leave, you could save thousands of francs because Schwyz has some of the lowest withholding tax rates for pension payouts in the country. This is a perfectly legal way to optimize your exit. To understand how these rates compare, refer to Swiss Taxes Explained: Federal, Cantonal, and Municipal Rates.
Reinvesting Your Payout Abroad
Once the money is in your bank account, the Swiss government no longer cares how you spend it. If you have moved back to your home country or a new expat hub, you might want to put that money to work. Some expats use services like Wise to transfer the large CHF sum into their new local currency with minimal fees. Others look toward diversifying into modern assets. If you are comfortable with high-risk, high-reward portfolios, you might look at Binance for crypto exposure, or Trade Republic for a more traditional ETF-based approach in Europe. Just remember that this money was originally intended for your old age—treat it with respect.
| Scenario | Destination of BVG Funds | Cash-Out Possible? |
|---|---|---|
| New Job in Switzerland | New Employer's Pension Fund | No |
| Sabbatical / Unemployed | Vested Benefits Account | No |
| Starting a Business | Personal Bank Account | Yes (With Proof) |
| Moving to EU/EFTA | Swiss Vested Benefits Account | Only Extra-Mandatory |
| Moving Outside EU | Personal Bank Account | Yes |
Administrative Hurdles and Paperwork You Cannot Ignore
The biggest mistake you can make when quitting is assuming HR will handle everything perfectly. You are the only person truly incentivized to track your money.
Finding Your Lost Pension Funds
If you have had multiple jobs in Switzerland and can't remember where all the pension pots went, don't panic. There is a centralized body called the Central Office for the 2nd Pillar. They act as a clearinghouse and can help you track down forgotten accounts. It is quite common for people to leave Working in Switzerland as an Expat: Jobs, Culture, and Employment Laws and forget about a small pot of money from a summer job or a short-term contract.
The Role of the Substitute Occupational Benefit Institution
As mentioned earlier, the "Auffangeinrichtung" is the safety net. If you are struggling to find a bank that will open a vested benefits account for you—which can sometimes happen to US citizens due to FATCA regulations—the Substitute Institution is legally required to accept your funds. While it isn't the most profitable place for your money, it is better than the money being held in limbo by a former employer who might eventually go out of business or merge with another entity.
Strategic Moves Before You Leave
If you know you are quitting to leave Switzerland, start the process of opening your Vested Benefits Account at least two months before your final day. You need the account to be "active" so that the transfer can happen smoothly. If you wait until you have already left the country, the paperwork becomes a nightmare of notarized signatures and apostilles. Make sure you understand How to Officially Leave the Church in Switzerland to Stop Kirchensteuer and other exit formalities, as these can also impact your final financial standing. If you are a US citizen, be particularly careful about reporting these accounts to avoid issues with FBAR and Form 8938: Reporting Swiss Bank Accounts for US Expats.
Disclaimer
The information provided in this guide is for informational purposes only and does not constitute financial, legal, or tax advice. Swiss pension laws and international social security treaties are subject to change and can vary significantly based on your individual citizenship, residency status, and specific employment contract. Always consult with a qualified Swiss tax advisor or pension specialist before making major decisions regarding your BVG assets.