The Three-Pillar Pension System: AHV, BVG, and Private Savings
Navigating the Swiss pension system often feels like trying to solve a Rubik’s cube while blindfolded. I remember staring at my first paycheck in Zurich, utterly baffled by the alphabet soup of deductions like AHV, ALV, and BVG, feeling like my salary was disappearing into a black hole. This guide breaks down the Three-Pillar system to help you secure your future and maximize your Swiss earnings today.
The Architecture of Swiss Retirement Planning
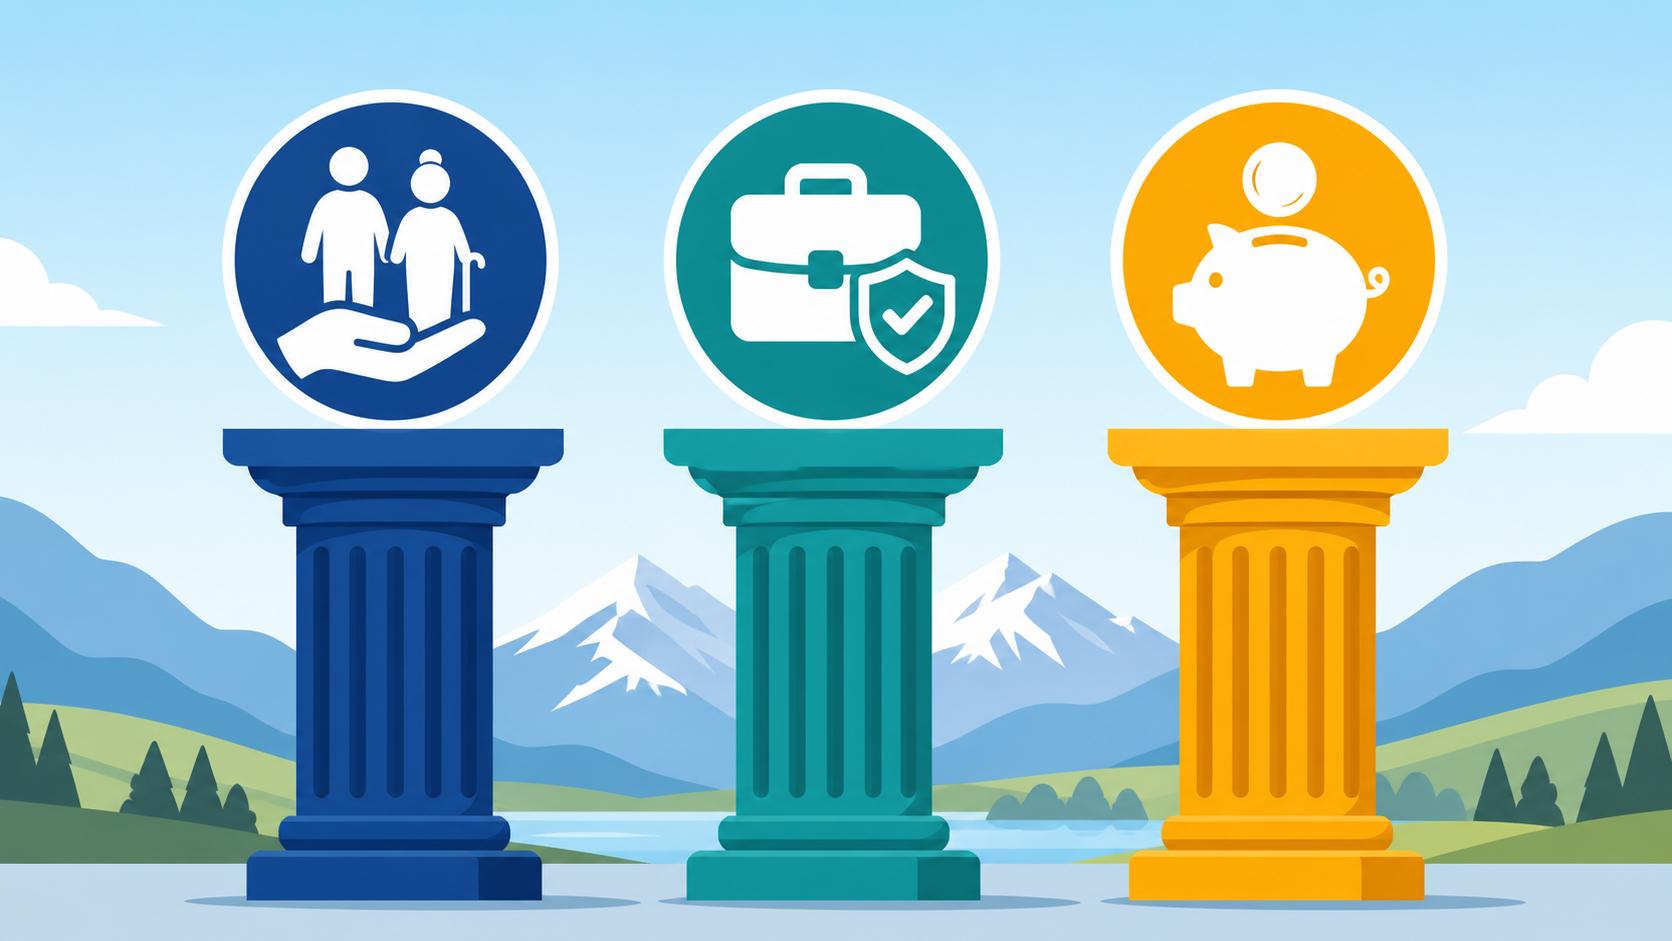
The Swiss pension system is built on a philosophy of shared responsibility between the state, the employer, and the individual. Unlike many countries that rely solely on a single state-funded pot, Switzerland spreads the risk across three distinct "pillars." This structure was designed to ensure that even after you stop working, you can maintain approximately 60% to 70% of your previous lifestyle. However, for those of us who arrive in Switzerland later in our careers, achieving that percentage requires a bit of strategic maneuvering and a deep understanding of how these layers interact.
The Philosophy of Swiss Social Security
At its heart, the Swiss system is a masterpiece of social engineering. The first pillar is purely about solidarity; it is designed to prevent poverty in old age by redistributing wealth from high earners to those with lower incomes. The second pillar is about maintaining your specific standard of living through your own professional efforts and your employer's contributions. Finally, the third pillar is your personal safety net, allowing for individual flexibility and significant tax advantages.
For an expat, understanding this philosophy is crucial because it dictates how you should manage your money. Many newcomers ignore their pension statements for the first five years, only to realize they have a massive "pension gap" because they didn't start contributing until their late 30s. In the Swiss mindset, your retirement is a project you start managing the day you register at the local Kreisbüro, not something you think about ten years before you stop working.
Why Expats Often Feel Overwhelmed by the Structure
The confusion usually stems from the different rules governing each pillar. Pillar 1 is mandatory for everyone, Pillar 2 is mandatory for most employees, and Pillar 3 is entirely optional. To make matters more complex, the rules for withdrawing these funds change depending on whether you are staying in Switzerland, moving to an EU country, or leaving Europe altogether. This is where most people get tripped up.
When I first arrived, I didn't realize that my "pension" wasn't just one account. It was actually three different pots of money held by different institutions with different investment rules. It takes time to realize that your second pillar is managed by a private foundation chosen by your employer, while your first pillar is a federal insurance scheme. Validating your frustration is important here: it is objectively more complex than the systems in the US, UK, or most of Europe, but once you "crack the code," it becomes a powerful tool for wealth building.
How Your Residence Permit Affects Your Pension Rights
Your status in Switzerland—whether you hold an L, B, or C permit—plays a subtle but important role in how you interact with these pillars. For example, those on a B permit often have their taxes and social security deducted at the source (Quellensteuer), which can make the tax benefits of Pillar 3a feel a bit more distant until you file a tax correction. On the other hand, C permit holders often have more flexibility in how they report their global assets and manage their retirement contributions.
It’s also worth noting that your permit type can influence your ability to take your pension with you if you leave. While the fundamental rights to the money are protected, the administrative hurdles can feel much higher for third-country nationals compared to EU citizens. Understanding Swiss Payslips: Deductions for AHV, ALV, and NBU is the first step in seeing exactly how your permit and your professional status translate into the numbers you see on your bank statement every month.
Pillar 1: Old-Age and Survivors Insurance (AHV/AVS)
Pillar 1, known as AHV in German or AVS in French, is the bedrock of the Swiss retirement system. It is a mandatory state pension that everyone living or working in Switzerland must contribute to. This is a "pay-as-you-go" system, meaning the money being deducted from your paycheck today isn't being saved for you personally; it’s being used to pay the pensions of people who are currently retired. In exchange, the next generation will pay for yours.
How AHV Contributions Are Calculated
As of 2026, the contribution rate for AHV is 10.6% of your gross salary. If you are an employee, this is split exactly down the middle: you pay 5.3%, and your employer pays 5.3%. There is no upper limit on the salary subject to these contributions, which is where the "solidarity" aspect comes in. A CEO earning CHF 1,000,000 pays the same percentage as a barista earning CHF 50,000, even though the maximum pension they can eventually receive is capped at a relatively modest amount.
The maximum monthly pension for a single person in 2026 is approximately CHF 2,450, provided they have contributed for the full 44 years. For couples, the combined pension is capped at 150% of the maximum single pension. If you’re an expat who arrived at age 35, you will never hit that 44-year mark, which is why your Pillar 2 and Pillar 3 become so vital. You can find more detail on these specific deductions in our guide on Understanding Swiss Payslips: Deductions for AHV, ALV, and NBU.
Missing Years and the Impact on Your Future Payouts
One of the biggest traps for expats is the "missing years" (Beitragslücken). Each year you don't contribute to the AHV after the age of 20 results in a permanent reduction of your eventual pension by about 2.3%. If you moved to Switzerland at 30, you already have 10 missing years. While you can sometimes "buy back" the last five years if you were already resident in Switzerland, you generally cannot fill gaps from before you arrived.
This is why many expats choose to make voluntary contributions if they take a sabbatical or if they are stay-at-home parents. The system allows for some flexibility, but the clock is always ticking. If you fail to manage these gaps, your Pillar 1 payout might barely cover your health insurance premiums by the time you retire. This is why we often suggest focusing heavily on the other two pillars to compensate for the "late start" most foreigners have in the Swiss system.
Claiming AHV Refunds if You Leave Switzerland Permanently
If you are a non-EU/EFTA citizen and you leave Switzerland permanently, you may be eligible to claim a refund of your AHV contributions. This is a massive financial decision. By taking the cash now, you forfeit any right to a Swiss state pension in the future. For many, having a lump sum to buy a house in their home country is more attractive than waiting 30 years for a monthly check of CHF 400.
There are specific rules, often referred to as The 5-Year Rule: Claiming an AHV Refund for Non-EU/EFTA Citizens, which dictate who can get their money back and when. Generally, you must have contributed for at least one year and be moving to a country that does not have a social security agreement with Switzerland. For Americans or Indians, the bilateral agreements can make this process quite specific, so always check the latest regulations before you book your one-way flight out of Zurich or Geneva.
Pillar 2: The Occupational Pension Scheme (BVG/LPP)
Pillar 2 is where the "real" money often sits for expats. Known as the BVG (German) or LPP (French), this is your company pension fund. Unlike Pillar 1, this money is yours. It sits in a personal account managed by your employer’s chosen pension foundation. Both you and your employer contribute monthly, and the funds are invested in a mix of stocks, bonds, and real estate to grow over time.
Mandatory vs. Voluntary Contributions
The law mandates that any employee earning over a certain threshold (currently around CHF 22,050 per year) must be enrolled in a BVG plan. Your contributions increase as you get older, starting at 7% of your "coordinated salary" in your 20s and rising to 18% by your late 50s. Again, your employer must pay at least half of this. Many "expat-friendly" companies offer "super-obligatory" plans where they contribute significantly more than the legal minimum, which is a key factor to consider when negotiating a job offer.
One of the best tax hacks in Switzerland is the "voluntary buy-in." If you have a pension gap (which almost every expat does), you can contribute extra cash into your Pillar 2. These contributions are 100% tax-deductible. If you are in a high-tax canton like Zurich or Geneva, a CHF 10,000 buy-in could save you CHF 3,000 or more in immediate taxes while boosting your retirement capital. You can read more about how this works in our deep dive on Pillar 2 (BVG): Understanding Your Swiss Occupational Pension.
Managing Your Vested Benefits (Freizügigkeitskonto)
What happens when you change jobs? This is a point of major confusion. Your old employer's pension fund cannot keep your money. They must transfer it to your new employer’s fund. If you take a break between jobs or leave Switzerland temporarily, your money goes into a "Vested Benefits Account" or Freizügigkeitskonto: Managing Vested Pension Benefits Between Jobs.
Some expats end up with four different vested benefit accounts scattered across different banks because they didn't realize they had to consolidate them. This is inefficient and usually results in your money sitting in low-interest cash accounts. By consolidating these into a single provider, you can often choose how the money is invested, giving you a much better chance of beating inflation over the long term.
Using Your Pension for a Home Purchase
Switzerland allows you to use your Pillar 2 capital for a very specific purpose: buying your primary residence. You can either withdraw the cash to use as part of your 20% down payment or "pledge" the funds as collateral to get a larger mortgage. This is a popular way for expats to break into the expensive Swiss real estate market.
However, there is a catch. If you withdraw the money, you reduce your future pension. Also, if you later sell the house, you generally have to pay the money back into the pension fund. It’s a complex tool that requires careful calculation. For more on the logistics, check out our guide on Withdrawing Pillar 2 for a Home Purchase in Switzerland. It's a great way to move from renting to owning, but you need to understand the long-term impact on your retirement.
Pillar 3: Private Savings and Tax Optimization
Pillar 3 is the "secret sauce" of the Swiss system. It is entirely voluntary, but for anyone earning a decent salary, it is almost foolish not to participate. It is divided into two parts: 3a (restricted) and 3b (unrestricted). For most expats, Pillar 3a is the primary focus because of its massive tax advantages.
Pillar 3a vs. Pillar 3b: Key Differences
Pillar 3a is "restricted," meaning you can only withdraw the money under specific circumstances: reaching retirement age, leaving Switzerland for good, starting your own business, or buying a home. In exchange for these restrictions, every franc you contribute (up to a yearly limit) is deducted from your taxable income. If you earn CHF 100,000 and contribute the maximum to your 3a, the tax office treats you as if you only earned roughly CHF 93,000.
Pillar 3b is "unrestricted." It’s essentially just a fancy name for your private savings, life insurance, or brokerage accounts. There are very few tax benefits to 3b in most cantons, but there are no restrictions on when you can take the money out. While 3a is a must-have for the tax break, 3b is where you might use platforms like Trade Republic to build a flexible investment portfolio that isn't tied to Swiss retirement laws.
Investing Your Pillar 3a for Maximum Growth
In the old days, a Pillar 3a was just a boring savings account at a big bank like UBS or Credit Suisse, earning 0.1% interest. Today, things have changed. You can now invest your 3a funds into 100% equity portfolios. For expats with 20+ years until retirement, this is the only way to go. Providers like VIAC, Finpension, or Frankly have revolutionized this space with low fees and high stock exposure.
When choosing a provider, look at the underlying fees. A 1% fee might not sound like much, but over 30 years, it can eat up a third of your final balance. I personally prefer the digital-first providers because they allow you to manage everything from an app and offer much better transparency than the traditional insurance-based 3a products. For a comparison of the top players, see Investing Your Pillar 3a: Finpension vs VIAC vs Frankly.
Tax Deductions and Contribution Limits for 2026
The Federal Social Security Office sets the limits for 3a contributions every year. For 2026, the limit for employees with a pension fund is expected to be CHF 7,258. If you are self-employed and don't have a Pillar 2, you can contribute up to 20% of your net income, capped at CHF 36,288.
It is vital to make your contribution before the December deadline. I’ve had friends wait until December 30th, only for the bank transfer to clear on January 2nd, meaning they lost the tax deduction for the entire year. You can find the exact details on Pillar 3a Limits 2026: CHF 7,258 for Employees, CHF 36,288 for Self-Employed to ensure you're maximizing your savings.
| Feature | Pillar 1 (AHV) | Pillar 2 (BVG) | Pillar 3a (Private) |
|---|---|---|---|
| Type | State Pension | Occupational Pension | Private (Restricted) |
| Mandatory? | Yes, for all | Yes, for employees | No, voluntary |
| Who pays? | You & Employer (50/50) | You & Employer (min 50/50) | Only You |
| Ownership | Collective/State | Personal Account | Personal Account |
| Tax Benefit | Deducted from gross | Deducted from gross | 100% Tax Deductible |
| Withdrawal | Only at retirement | Retirement, Home, Leaving CH | Retirement, Home, Leaving CH |
Navigating the Financial Logistics of Swiss Retirement
As an expat, your financial life is rarely confined to one country. You might be earning in CHF, but you have student loans in USD, a mortgage in GBP, or a family you support in EUR. Managing the intersection of your Swiss pension and your international life requires some modern financial tools.
Moving Abroad and Withdrawing Your Pension Funds
The day you decide to leave Switzerland is the day your pension strategy faces its biggest test. If you move to a non-EU country, you can usually withdraw both your Pillar 2 (the mandatory and extra-mandatory parts) and your Pillar 3a in cash. This can be a life-changing amount of money—hundreds of thousands of francs for long-term expats.
The process of Leaving Switzerland Financially: Closing Accounts and Pension Payouts involves a lot of paperwork. You'll need to prove you've deregistered from your commune and show proof of your new residence abroad. Be prepared for the "withholding tax" (Quellensteuer) that Switzerland takes upon withdrawal. A pro-tip: if you move your vested benefits to a canton with low withdrawal taxes (like Schwyz) before you leave, you can save thousands in fees.
Neobanks and Investment Tools for Pension Management
While your Pillars 1 and 2 are somewhat "locked" into the Swiss ecosystem, your Pillar 3 and general savings can be managed more dynamically. For moving money out of Switzerland or bringing funds in for a Pillar 2 buy-in, using a traditional bank is a recipe for losing 3% in hidden exchange rate fees. I always use Wise for these transfers because they use the real mid-market rate, which is essential when you're dealing with five-figure pension sums.
For your Pillar 3b (unrestricted savings), you might look at Trade Republic. They offer a simple way to invest in ETFs and even earn interest on your uninvested cash, which is often higher than what Swiss retail banks offer. If you're someone who believes in the future of digital assets, Binance provides the gateway for crypto exposure, though I'd always suggest keeping that as a very small "satellite" part of your overall retirement strategy, never the core.
Protecting Your Retirement from Inflation and Currency Risk
The Swiss Franc (CHF) is one of the world's strongest currencies, which is a blessing while you live here. However, if you plan to retire in a country with a different currency, you are exposed to currency risk. If the CHF weakens (unlikely as that seems today), your "Swiss fortune" might not buy as much as you hoped.
Conversely, if you stay in Switzerland, inflation is your primary enemy. Even the 2-3% inflation we've seen recently can erode the purchasing power of a cash-heavy Pillar 2 over 20 years. This is why I advocate for equity-heavy Pillar 3a accounts and voluntary Pillar 2 buy-ins that are invested aggressively. You aren't just saving money; you are protecting your future self's ability to buy groceries and pay rent in one of the world's most expensive countries.
Common Pitfalls and Expert Tips for Expats
After years of helping friends navigate this, I’ve noticed a few patterns. The people who retire comfortably in Switzerland (or take a massive pot of money with them) are the ones who treat their pension as an active investment, not a passive deduction.
The Danger of the Pension Gap
The biggest mistake is assuming the "system" will take care of you. If you moved to Switzerland at age 40, the system is only designed to give you about 25 years of contributions. This will result in a massive shortfall. You must proactively calculate this gap. Most pension funds will provide a "simulated" statement showing what you will get at 65. If that number looks low, it’s because it is.
The solution is a combination of Exactly How to Claim the CHF 7,258 Pillar 3a Tax Deduction for 2026 and aggressive voluntary buy-ins to Pillar 2. Every year you don't max out your 3a is a tax gift you are giving to the Swiss government that you will never get back.
Understanding Your Annual Pension Certificate
Every January, you will receive a "Vorsorgeausweis" from your employer's pension fund. It looks like a complicated spreadsheet, but you only need to look at three numbers:
- The Current Value: How much cash is in there today.
- The Projected Value: What will be there at age 65 if you keep your current salary.
- The Purchase Potential (Einkaufspotenzial): How much extra tax-deductible cash you are allowed to pump into the fund.
I keep a folder of these every year. Watching that "Current Value" grow because of both contributions and market gains is one of the most satisfying parts of expat life in Switzerland. It turns the "pain" of the high cost of living into the "gain" of a high-value retirement.
Coordinating Your Swiss Pension with Foreign Social Security
If you’ve worked in the UK, the US, or elsewhere, you likely have "social security credits" or private pensions there too. Switzerland has social security agreements with many countries to ensure you don't lose these rights. However, they don't happen automatically. You usually have to claim them separately when you reach the retirement age of that specific country.
When you finally retire, you might be receiving a small state pension from the UK, a 401k payout from the US, and your three pillars from Switzerland. Managing the tax implications of these multi-country payouts is a job for a specialist, but the groundwork is laid today by keeping meticulous records of every year you worked in every country.
Disclaimer
The information provided in this guide is for informational purposes only and does not constitute financial, legal, or tax advice. Pension laws and tax regulations in Switzerland are subject to frequent changes. Always consult with a qualified Swiss tax advisor or financial planner before making significant financial decisions, especially regarding pension withdrawals or voluntary contributions.