Life Insurance in Switzerland: Term vs Pillar 3a-Linked Policies
Most expats arrive in Switzerland and are immediately overwhelmed by the sheer volume of "mandatory" and "recommended" insurance policies. While you likely already have your health insurance sorted, the question of life insurance often falls through the cracks until a mortgage broker or a pushy financial advisor brings it up. This guide solves the confusion between pure term life insurance and the complex, savings-linked policies found within the Pillar 3a system, helping you protect your family without falling into common expat traps.
Why the Swiss Pension System Often Isn't Enough for Families
When you first start working in Switzerland, you’ll notice deductions on your payslip for the first pillar (AHV) and the second pillar (BVG). Many newcomers assume these state and occupational pensions provide a sufficient safety net. However, if you are the primary breadwinner, the reality is often quite sobering. The survivor’s benefits provided by the first and second pillars typically only cover about 60% to 70% of your previous income. For a family living in a high-cost city like Zurich or Geneva, a 30% drop in household income can be catastrophic, especially if you have a significant mortgage or children in private schooling.
Understanding The Three-Pillar Pension System: AHV, BVG, and Private Savings is the first step in recognizing where your "coverage gap" lies. Most expats find that their existing social security benefits won't cover the full cost of staying in their current apartment or maintaining their standard of living if a spouse passes away. This is where private life insurance comes into play. It isn't just about "death benefits"; it is about ensuring your partner isn't forced to leave the country or sell the family home during an already traumatic time.
In my years living here, I’ve seen many families overlook this because they feel "over-insured" already. But Switzerland is an expensive place to die. Between funeral costs, estate settlement, and the potential loss of a residency permit for a dependent spouse, having a liquid cash injection from a life insurance policy is often the only thing that keeps an expat family's life from unraveling.
Term Life Insurance: The Pure Protection Approach
Term life insurance, known in German as Risikolebensversicherung, is the most straightforward form of protection you can buy. You pay a monthly or annual premium for a set period—say, 20 years—and if you pass away during that term, the insurance company pays a tax-free lump sum to your beneficiaries. If you survive the term, the policy simply expires, and there is no cash value to "cash out."
This model is ideal for expats because of its transparency and low cost. Because you aren't trying to save money through the policy, the premiums are dedicated entirely to the "risk" of death. For a healthy 35-year-old, a payout of CHF 500,000 might only cost a few hundred francs per year. This makes it a highly efficient way to cover specific liabilities, such as the outstanding balance on a home loan. If you are currently navigating Mortgages in Switzerland: The 20% Down Payment and Amortization Rules, your bank may even require a term life policy as collateral to ensure the mortgage can be serviced if one partner dies.
The flexibility of term insurance is its greatest asset for the mobile expat. If you decide to leave Switzerland after five years, you can simply cancel the policy or, in some cases, convert it. Unlike savings-linked versions, there are no "surrender fees" or complicated calculations regarding how much of your "investment" you get back. You’ve paid for protection, you received it, and you move on. For those who manage their own investments using low-cost platforms or currency tools like Wise to move money between borders, keeping insurance and investments separate is almost always the more profitable path.
Pillar 3a-Linked Life Insurance: The Hybrid Savings Model
In Switzerland, you will frequently be pitched "mixed" life insurance (Gemischte Lebensversicherung). These policies are often packaged as part of your Pillar 3a. The pitch is enticing: "Why pay for insurance and get nothing back? With this policy, your premiums go toward life insurance AND a savings pot that grows over time, all while giving you a massive tax deduction!"
While the tax deduction is real, these policies are a common source of frustration for the expat community. Because the policy is "linked" to the Pillar 3a, it follows strict federal rules. You can find more detail on these in Pillar 3a in 2026: Tax Deductions, Limits, and Investment Options. The problem arises from the lack of flexibility. A mixed policy is essentially a long-term contract, often spanning 30 to 40 years. If you need to cancel it early because you are moving back to the UK, US, or EU, you will likely face a "surrender value" (Rückkaufswert) that is significantly lower than the total premiums you’ve paid. In the first few years of such a policy, the surrender value is often zero because your initial premiums go toward the broker’s commission and administrative costs.
Furthermore, these policies combine two very different financial goals. Your need for life insurance usually decreases as you get older and your mortgage is paid off, whereas your need for retirement savings increases. By "locking" them together, you lose the ability to adjust your insurance coverage without affecting your savings. I always tell newcomers: if a broker is pushing a 3a life insurance policy, ask them to show you the surrender value table for years 1 through 10. That usually ends the "investment" argument pretty quickly.
Comparing Costs, Flexibility, and Tax Benefits
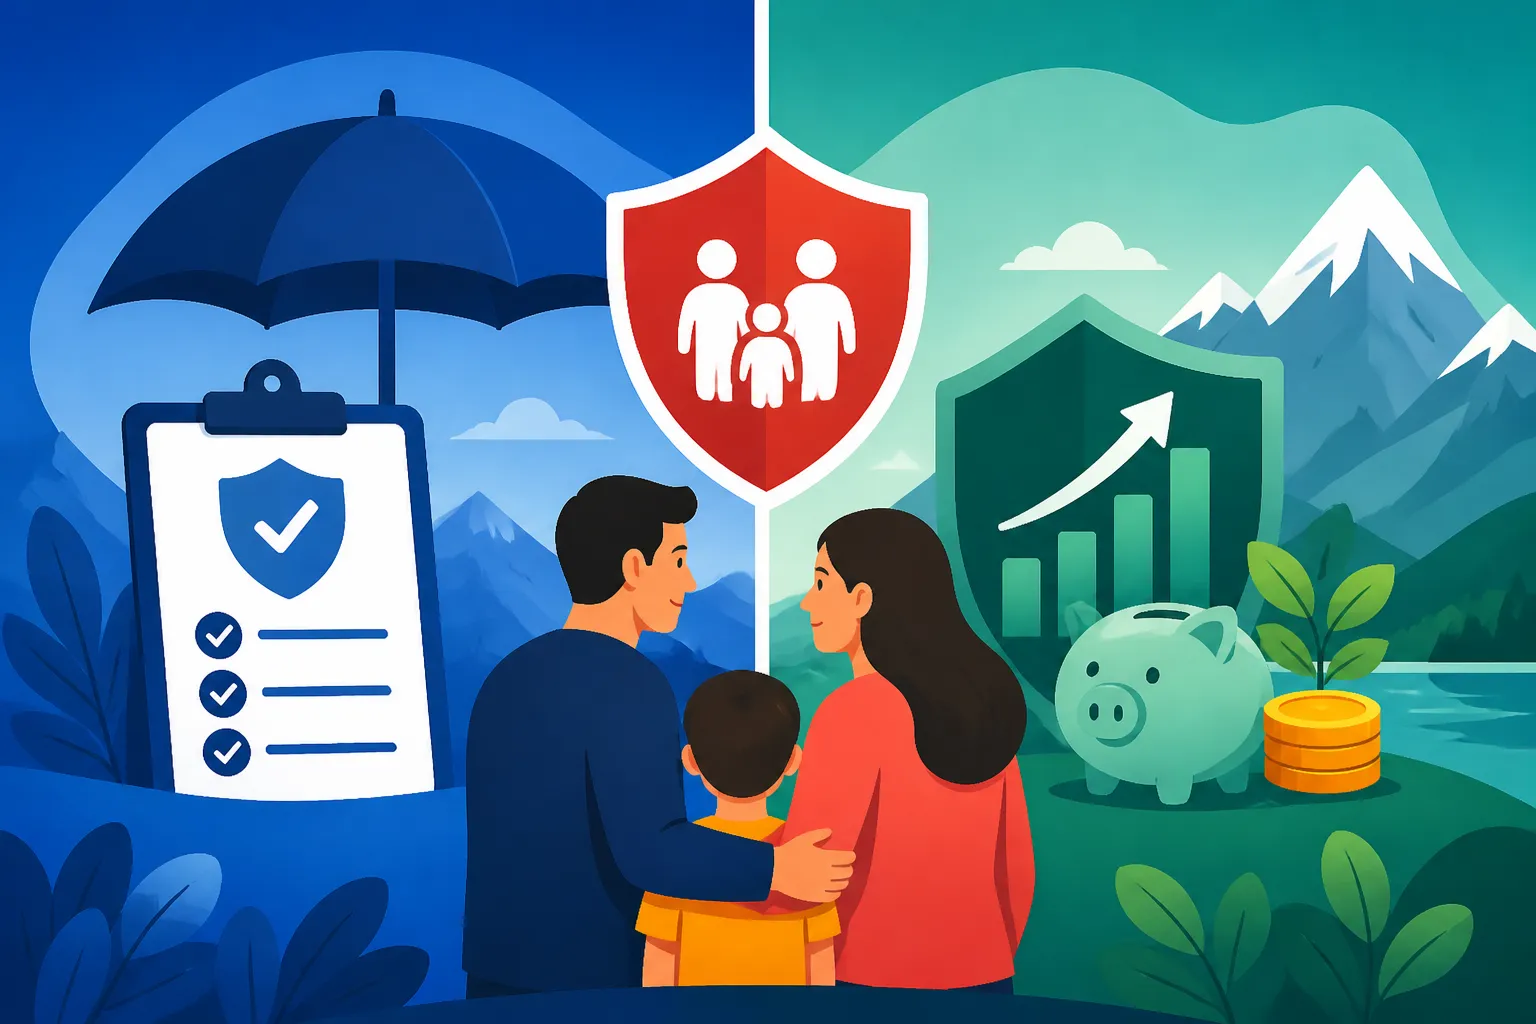
To help you visualize the difference, let’s look at how these two options stack up for a typical expat professional.
| Feature | Term Life Insurance (Risiko) | Linked Pillar 3a Life Insurance |
|---|---|---|
| Primary Goal | Pure protection/death benefit | Savings + Protection |
| Premium Cost | Low (only covers the risk) | High (covers risk + savings) |
| Tax Deductibility | Limited (under Pillar 3b) | High (fully deductible up to 3a limit) |
| Flexibility | High (cancel anytime) | Very Low (long-term contract) |
| Exit Strategy | Simple cancellation | Complex; often involves financial loss |
| Cash Value | None | Accrues over decades |
| Best For | Mortgages and young families | Long-term residents with no investment DIY |
The tax benefit of the linked 3a policy is the main "hook." By contributing to a 3a, you can reduce your taxable income significantly. When you are Filing a Swiss Tax Return (C Permit or High Earners on B Permit), this can result in thousands of francs in savings. However, you can get the same tax break by opening a simple, bank-based Pillar 3a account and buying a separate, cheap term life policy. This "unbundled" approach gives you the tax savings without the 30-year handcuffs.
If you are a US citizen, the linked policies are an even bigger headache. The IRS often views these Swiss "insurance-investments" as Passive Foreign Investment Companies (PFICs), which can lead to nightmare tax reporting requirements. In these cases, consulting a specialist firm like Taxes for Expats is essential to ensure you aren't accidentally creating a massive tax liability back home while trying to save a few francs in Switzerland.
The Role of Pillar 3b in Life Insurance Planning
If you have already maxed out your Pillar 3a contributions but still feel you need more coverage or want a place to park savings with an insurance component, you might look at Pillar 3b. This is the "unrestricted" pillar. There are fewer tax advantages here, but there are also fewer rules. Policies in Is Pillar 3b Worth It for Expats? Tax Inefficiencies Explained don't have the same strict withdrawal ages as the 3a, making them slightly more attractive for someone who might leave the country before age 65.
However, for most expats, Pillar 3b life insurance is rarely the optimal choice. The premiums are paid with "after-tax" money, and while the eventual payout might be tax-exempt under certain conditions, the management fees inside these insurance wrappers often eat up any potential gain. If you have extra cash, you are usually better off putting it into a diversified brokerage account. If you need to send that money abroad or manage multiple currencies, using Wise to avoid high bank spreads will likely "earn" you more than the meager interest rates offered by a 3b insurance savings plan.
Critical Mistakes Expats Make When Buying Coverage
One of the biggest mistakes I see is expats failing to account for the "inflation of life." A policy for CHF 300,000 might have seemed like a lot when you first moved into a small apartment in Basel, but once you have two kids and a larger home in the suburbs, that amount barely covers three years of expenses. You should review your coverage every time your family status or debt levels change.
Another pitfall is the "constant premium" trap. Some brokers will offer you a policy where the premium stays the same for 30 years. While this sounds good, remember that the risk of you dying at age 30 is much lower than at age 60. You are essentially overpaying in your youth to "subsidize" your older self. For expats who may not even be in Switzerland by age 60, it often makes more sense to take a "level term" or "decreasing term" policy that matches their actual liabilities.
Finally, don't forget about the "disability" component. Many life insurance policies in Switzerland allow you to add a "waiver of premium" or a disability income rider. In a country where Mandatory and Optional Insurance: Liability, Legal, and Household coverage is the norm, protecting your ability to earn an income is arguably more important than insuring against death. If you become unable to work due to illness, the insurance company takes over your premium payments, ensuring your savings goal is still met.
How to Choose the Right Path for Your Situation
If you are a "B Permit" holder and aren't 100% sure you will be in Switzerland for the next 20 years, the advice is almost always to stick with Term Life Insurance. It is cheap, it does exactly what it says on the tin, and it doesn't punish you for moving. You can then take the money you saved on premiums and put it into a flexible Pillar 3a bank account where you can choose your own investment strategy.
For those who are settled, perhaps on a "C Permit" or with a Swiss spouse, and who struggle with the discipline of saving, a linked policy might provide a forced savings mechanism. But even then, you must be aware of the high costs. Before signing anything, check your current "survivor's pension" from your 2nd pillar. You can find this on your annual pension statement (Versicherungsausweis). Subtract that amount from what your family actually needs to survive; the gap is the amount of term insurance you should buy.
Managing your global finances requires a holistic view. Whether it’s using Taxes for Expats to stay compliant with your home country or using Wise to manage your multi-currency life, your insurance should be a tool that serves you, not a burden that restricts you. Switzerland offers world-class financial security, but only if you navigate the options with a healthy dose of expat skepticism.
Disclaimer
This article is for informational purposes only and does not constitute professional financial, legal, or tax advice. Swiss insurance laws and tax regulations are subject to change. You should consult with a qualified financial advisor or tax professional who understands the specific needs of expats before committing to any long-term insurance contract in Switzerland.