Why Almost Every Swiss Landlord Requires Privathaftpflicht Insurance
Privathaftpflicht insurance is required by almost every Swiss landlord to cover expensive tenant damages and accidental property losses during rentals.
Privathaftpflicht insurance is required by almost every Swiss landlord to cover expensive tenant damages and accidental property losses during rentals.
Swiss shared apartment residents face solidary liability for media fees, meaning everyone shares legal responsibility regardless of whose name appears.
University student status and welfare assistance status determine the specific rules for obtaining a Swiss Serafe media fee exemption.
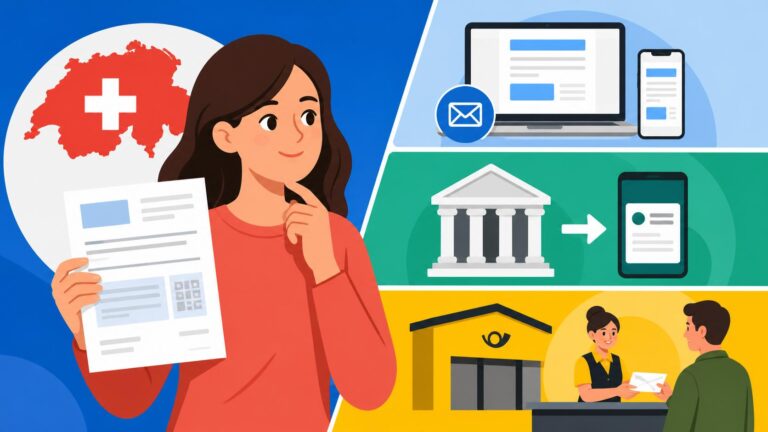
Payment methods for the Swiss Serafe media tax include eBill, manual bank transfer, and cash payments at the post office.
Swiss Pillar 3b insurance policies often trap expats with high fees and wealth taxes. Discover flexible alternatives for building wealth.
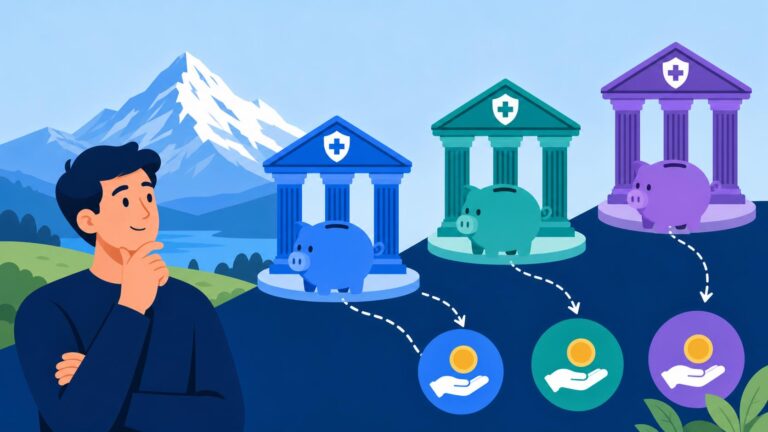
Multiple Pillar 3a accounts let expats avoid high progressive Swiss retirement taxes through staggered, multi-year lump sum withdrawals.
Swiss tax rules and permit statuses determine how residents claim the CHF 7,258 Pillar 3a deduction for the 2026 tax year.
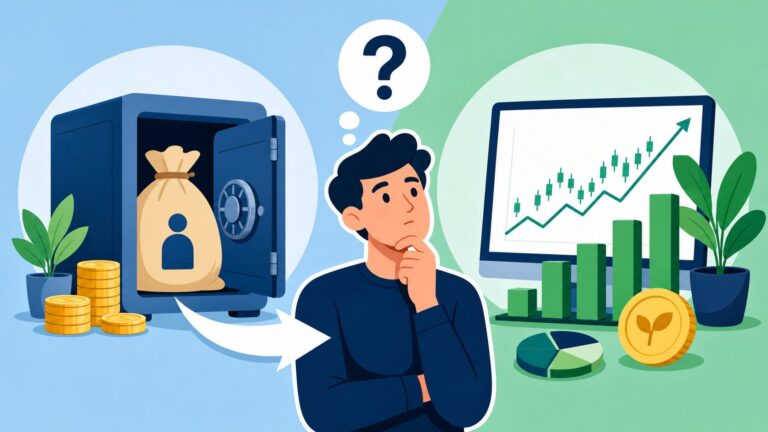
Swiss vested benefits from your second pillar can move from stagnant bank accounts into diversified global stock market investments.
Your Swiss BVG pension requires careful transfer into a vested benefits account, a new employer fund, or cash upon leaving your job.
Voluntary AHV contributions let expats identify Swiss pension gaps using the IK statement and pay missing years within strict deadlines.