Hospital Choice in Switzerland: Can You Pick Any Hospital on Basic Insurance?
It's incredibly frustrating when you first arrive in Switzerland and start navigating the healthcare system, especially when it comes to something as fundamental as choosing a hospital. Many of us arrive assuming a certain level of flexibility we might have had back home, only to discover that the Swiss system, while excellent, operates with its own unique set of rules. This guide will cut through the confusion and explain exactly how your basic health insurance (KVG/LAMal) dictates your hospital choices here, helping you avoid nasty surprises.
The Reality of Basic Health Insurance (KVG/LAMal) and Hospital Choice
When you first sign up for basic health insurance in Switzerland, you’re fulfilling a legal requirement, which is a huge relief to get sorted within the mandatory 90-day registration window. But what that basic insurance actually covers, especially for hospital stays, often comes as a surprise to newcomers. It's not a free pass to pick any shiny, modern clinic you fancy across the country; far from it.
The 'Local List' Principle
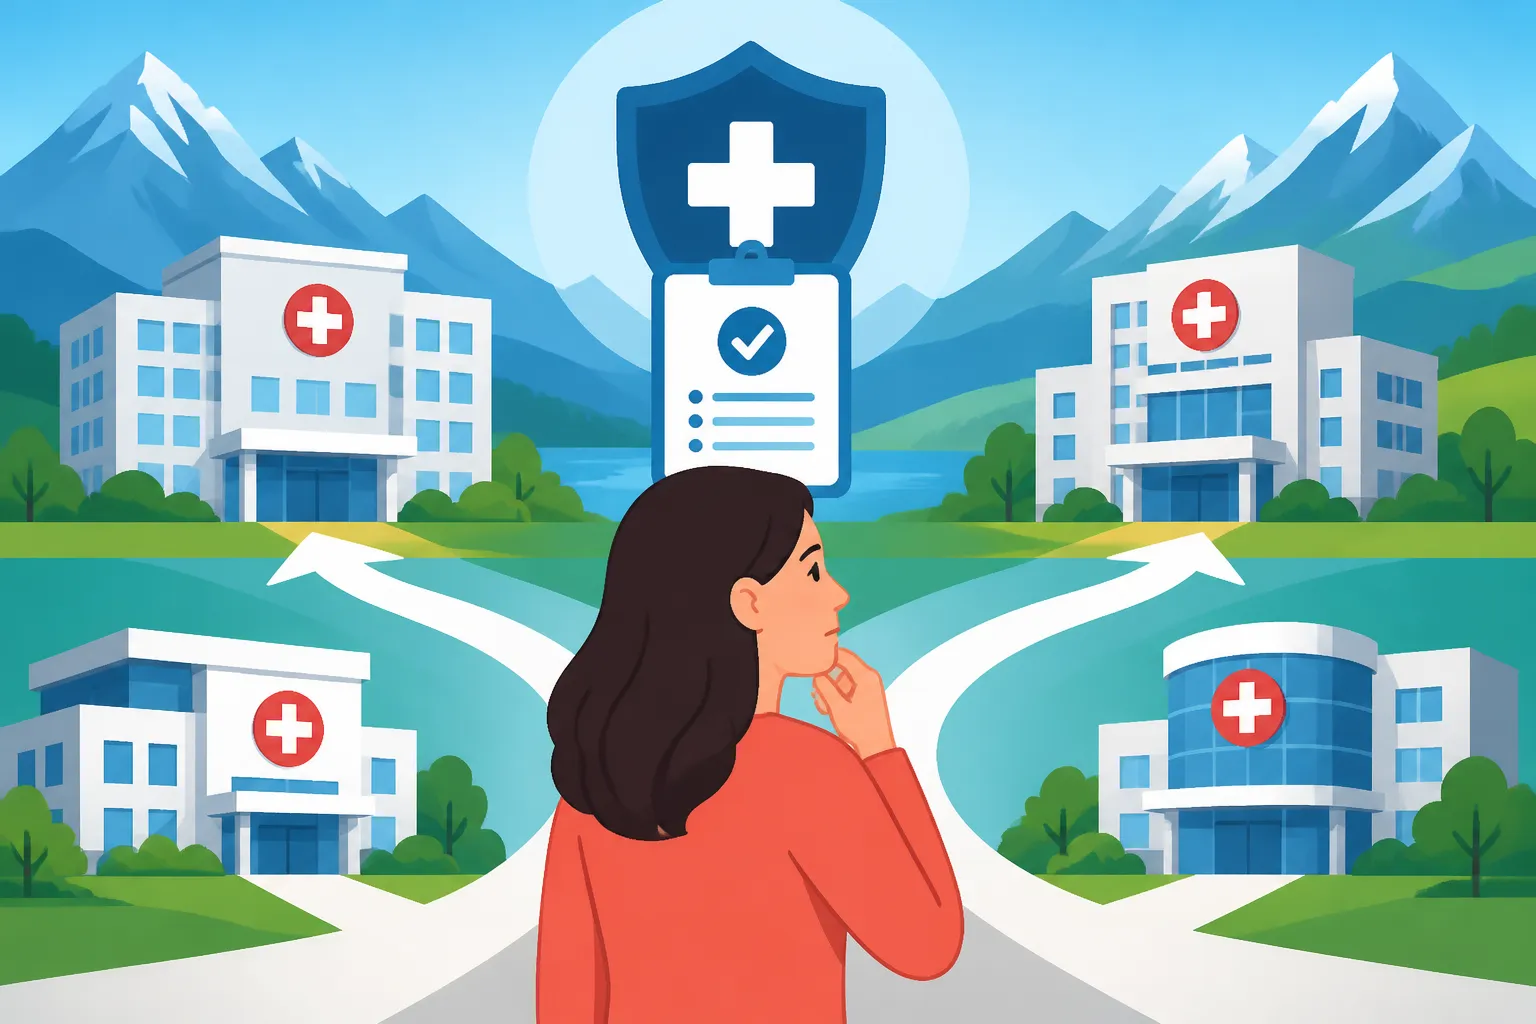
The fundamental principle here is deeply rooted in how the Swiss healthcare system is structured and funded. Your mandatory basic health insurance (KVG/LAMal) primarily covers treatment in a general ward (Allgemeine Abteilung) in a hospital that is listed on your canton's official hospital list. This isn't just a suggestion; it's a hard rule. Each canton maintains a list of hospitals with which it has contracts and helps subsidize, ensuring that its residents have access to necessary medical care. So, if you live in, say, Canton Zurich, your basic insurance will typically only cover the costs of a general ward stay in a hospital on the Zurich cantonal list.
Imagine you've been living in Switzerland for a few months, and you need a non-emergency surgery, perhaps for a hernia or a routine procedure. You might have heard glowing reviews about a particular specialist or a hospital in another canton, or even one of those beautiful private clinics with lake views. If that hospital isn't on your cantonal list, or if you don't have supplementary insurance specifically covering out-of-canton treatment, your basic insurance will only cover the cost up to what the treatment would have cost in a hospital on your canton's list. You, my friend, would be on the hook for the difference, and let me tell you, that difference can be astronomical. It's a bitter pill to swallow when you thought you were covered, and it really highlights why Understanding KVG/LAMal: Mandatory Basic Health Insurance Explained is so crucial from day one.
When Can You Choose a Different Hospital?
Now, before you panic and think all choice is gone, there are specific circumstances where you do have more flexibility or where basic insurance will cover treatment beyond the strict cantonal list.
Firstly, in an emergency, your basic insurance will cover necessary treatment in the nearest appropriate hospital, regardless of cantonal borders or whether it's on your "list." Your life or immediate health takes precedence, as it absolutely should. If you collapse on a hiking trail in Valais, and the nearest hospital is in Sion, you will be treated there, and your basic insurance will pick up the tab for the general ward care. Don't ever hesitate to call for help in a crisis; understanding Emergency Medical Services: Ambulances, REGA, and Crisis Protocols is important, but getting care is paramount.
Secondly, if a specific, specialized medical treatment or procedure is not available in any hospital on your canton's list, or if the waiting list is unreasonably long, your doctor can make a referral to an out-of-canton hospital. This requires prior approval from your health insurance provider, who will verify that the treatment truly cannot be adequately provided locally. This isn't a loophole for convenience but a provision for genuine medical necessity. It's a careful balance, and your insurance company will scrutinize such requests.
Thirdly, and this is where many expats get confused, supplementary health insurance (VVG) can significantly expand your choices. While your basic KVG insurance is standardized, VVG policies are private contracts that offer a range of additional benefits. Many VVG plans include coverage for semi-private or private wards, allowing you to choose any hospital in Switzerland that offers these categories, often even internationally. This is a common path for those who value greater comfort and choice. However, it's vital to remember that these are separate policies and come with their own premiums and conditions, which you can read more about in Supplementary Health Insurance (VVG): What It Covers and When to Buy It.
Understanding Hospital Tiers and What Your Basic Insurance Covers
The Swiss hospital system operates on a tiered basis, and your basic insurance strictly aligns with one of these tiers. Understanding this is key to managing expectations and avoiding unexpected costs.
General Ward (Allgemeine Abteilung) – The Standard
Your mandatory basic health insurance (KVG/LAMal) covers you for treatment in the general ward of a public or contracted hospital on your canton's list. What does this actually mean in practice?
Typically, a general ward involves:
- Multi-bed rooms: You'll likely share a room with two to four other patients. This is the norm. Privacy is limited, and shared bathrooms are common.
- Treatment by the duty doctor: You will be treated by the team of doctors assigned to the general ward, not necessarily a specific "chief physician" or "senior consultant" by name. While the quality of care is high, you don't have the right to choose your specific treating physician.
- Standard amenities: You get the medical care you need, but don't expect plush robes, gourmet menus, or private TV screens. It's functional, clean, and efficient, but definitely not a hotel experience.
For many expats, especially those coming from countries with national healthcare systems or where private rooms are more common, this can be a bit of a culture shock. While the medical expertise is consistently excellent, the comfort level might be different from what you're used to. It's important to set your expectations accordingly. This standard coverage applies even to seemingly minor things like your post-operative follow-ups or physiotherapy during your stay; everything adheres to the general ward protocol.
The Cost Implications of Upgrading
If you desire more comfort, privacy, or the ability to choose your doctor, you'll be looking at the next tiers: semi-private (halbprivat) or private (privat) hospital stays.
- Semi-private (Halbprivat): This typically means a two-bed room, often with an en-suite bathroom, and treatment by a senior doctor or the head of department.
- Private (Privat): This usually offers a single room, often with hotel-like amenities, and the right to be treated by the chief physician (Chefarzt) of the department.
Here's the crucial part: basic insurance will never cover these upgrades. The costs for semi-private or private treatment are significantly higher than the general ward rates, and if you opt for them without adequate supplementary insurance, you will be personally responsible for the entire difference. This is why many long-term expats, once they've settled, consider purchasing supplementary hospital insurance. These VVG policies are designed specifically to bridge this gap, offering you greater flexibility in hospital choice (often nationwide) and a higher tier of comfort and medical attention.
For those just arriving or on shorter-term visas, products like SafetyWing might provide excellent travel and emergency medical coverage outside the rigid Swiss KVG system, perfect for that initial journey or trips abroad. However, for continuous residency in Switzerland, you'll quickly realize that SafetyWing's temporary nature and focus on travel don't replace the need for comprehensive Swiss KVG basic insurance or the VVG supplementary plans designed for long-term residents seeking more hospital choice within the country. It's a completely different ballgame once you're officially a resident.
Navigating Hospital Stays: Practical Advice for Expats
Dealing with a hospital stay, whether planned or unexpected, can be daunting in any country, let alone one with a new language and a different system. Knowing the ropes can alleviate a lot of stress.
Planned vs. Emergency Admissions
There's a significant difference in how you approach planned procedures versus sudden emergencies.
For planned admissions, communication is your best friend. Once your doctor recommends a hospital stay or surgery, you should:
- Confirm the Hospital's Status: Double-check that the recommended hospital is on your canton's official list for basic insurance coverage, or confirm that your supplementary insurance (if you have it) covers the chosen facility and ward class nationwide.
- Get Prior Approval (if needed): If your doctor is referring you to an out-of-canton hospital for a specialized treatment not available locally, ensure your insurance company provides written prior approval. Don't assume anything; an email or call isn't enough – get it in writing!
- Understand Your Insurance Model: If you're on a restricted insurance model like Telmed or HMO, your family doctor (Hausarzt) or the Telmed hotline will typically manage your referrals, including to hospitals. Bypassing this process can lead to reduced or denied coverage. It's essential to understand Comparing Health Insurance Models: Telmed, HMO, Family Doctor, and Standard to know your obligations.
For emergency admissions, the good news is that immediate medical necessity trumps administrative hurdles. If you experience a sudden illness or accident, seek help immediately. Dial 144 for an ambulance, or head to the nearest emergency room. Your basic insurance will cover the costs for the general ward, regardless of whether it’s on your specific cantonal list. However, once the immediate emergency is over and you are stable, your insurance provider might require a transfer to a hospital on your canton's list if continued long-term care is needed, though this is rare and handled by medical professionals. Just be aware that emergency rooms in Switzerland can have significant waiting times for non-life-threatening issues, so understanding Emergency Rooms in Switzerland: Triage, Waiting Times, and Billing can help manage expectations.
The Role of Your Doctor and Referral System
Your general practitioner (Hausarzt) or specialist plays a pivotal role in your hospital choice, particularly if you're on a managed care insurance model. They act as your gatekeeper and guide within the system.
In a standard insurance model, your family doctor can refer you to a specialist or hospital. In a family doctor model (HMO or Hausarztmodell), they are the first point of contact for almost all medical issues and must provide a referral for specialist or hospital treatment. This centralized approach aims to streamline care and prevent unnecessary consultations. If you bypass your family doctor, your insurance might not cover the costs. For expats, finding an English-speaking family doctor who understands the system can be invaluable; this is a resource many wish they had from the start.
It's also worth noting that if you have a specific need, such as for a particular type of surgery or ongoing care, your doctor will usually recommend a hospital where they have connections or believe you'll receive the best care within the KVG framework. For specific cases where you might consider trying to Accessing Specialists Without a Referral: What Your Insurance Model Allows, be sure you fully grasp your policy's terms to avoid surprise bills.
Billing Systems and Unexpected Costs
The Swiss medical billing system can be complex. You'll primarily encounter two systems:
- Tiers Garant: This means you receive the bill directly from the hospital or doctor, pay it, and then submit it to your insurance for reimbursement.
- Tiers Payant: Here, the hospital or doctor sends the bill directly to your insurance company, which then pays its share and sends you a bill for your deductible (franchise) and co-payment (Selbstbehalt).
Many hospitals operate on the Tiers Garant system, especially for non-emergency services, meaning you might see large bills initially. This is normal, but it underscores the importance of verifying coverage before a planned procedure. Understanding How to Pay Medical Bills: Tiers Garant vs. Tiers Payant Billing Systems is critical.
The most common source of unexpected costs for expats related to hospital choice stems from:
- Choosing an unapproved hospital/ward: As discussed, if you pick a hospital not on your canton's list, or a semi-private/private ward without corresponding supplementary insurance, you will pay the difference.
- Not following your insurance model's rules: Bypassing your family doctor in an HMO model for a direct specialist or hospital visit can lead to denied claims.
- Deductibles and co-pays: Even with full basic coverage, you will always be responsible for your chosen annual deductible (franchise) and a 10% co-payment (Selbstbehalt) up to a maximum of CHF 700 per year. It's vital to calculate Out-of-Pocket Maximums: Calculating Your True Annual Healthcare Costs to understand your true financial exposure.
To reiterate, while basic insurance provides excellent medical care, it is not designed for maximum choice or luxury. It's designed to provide necessary and effective treatment within a structured, cost-controlled framework. If you prioritize choice and comfort in your hospital experience, supplementary insurance is the route you'll need to explore.
| Feature | Basic Health Insurance (KVG/LAMal) | Supplementary Hospital Insurance (VVG) |
|---|---|---|
| Hospital Choice | Restricted to canton's official list (general ward), nearest for emergencies. | Often nationwide choice (any recognized hospital), depending on policy. |
| Ward Class | General ward (multi-bed room). | Semi-private (2-bed room) or Private (1-bed room), depending on policy. |
| Doctor Choice | Duty doctor/team assigned to general ward. | Senior doctor or chief physician, depending on policy. |
| Referral System | Often requires referral via GP/Telmed for specialist/hospital. | May offer more direct access to specialists without prior referral. |
| Cost Control | Fixed premiums, deductible, and co-pay (CHF 700 max). | Additional premiums; covers costs beyond basic KVG for higher tiers. |
| Coverage Out-of-Canton | Only if medically necessary and unavailable locally (with prior approval). | Often covers preferred hospital choice across Switzerland. |
| Amenities | Standard, functional. | Enhanced comfort, privacy, and hotel-like services. |
Disclaimer
Please remember that this guide provides general information based on current Swiss regulations. Healthcare laws and insurance conditions can change. It is always best to consult directly with your specific health insurance provider and, if necessary, seek professional advice to understand your individual coverage and obligations in Switzerland.