How to Send Money from Switzerland to India Cheaply
Sending money back to India while living in Switzerland can feel like you are being penalized for your hard work. Between the high flat fees charged by traditional Swiss banks and the sneaky markups on the CHF-INR exchange rate, you can easily lose hundreds of francs a year. This guide breaks down the cheapest, fastest, and most reliable ways to transfer your Swiss salary home without the bank-sized headache.
The Reality of Remittance from Switzerland to India
When you first arrive and set up your life, perhaps following a Financial Checklist for Your First 30 Days as an Expat in Switzerland, your primary focus is usually just getting a IBAN so you can receive your salary. However, once that first paycheck hits your account and you see the deductions for OASI and ALV, the reality of the high cost of living sets in. You want to make sure that every Swiss Franc you send to India actually arrives there.
The traditional banking sector in Switzerland is world-renowned for stability, but it is notoriously expensive for retail currency exchange. If you use a standard bank, you are hit twice: first by a "processing fee" (often between 20 CHF and 50 CHF) and second by an exchange rate that is 3% to 5% worse than the one you see on Google. For a veteran expat, this is simply unacceptable. We are already navigating the complex world of Banking and Finance for Expats in Switzerland: The 2027 Guide, so we shouldn't have to settle for poor remittance rates.
Hidden Costs in the CHF to INR Exchange Rate
Most people look at the "transfer fee" and think that is the total cost. It isn't. The real cost is hidden in the "spread." This is the difference between the mid-market exchange rate (the one banks use to trade with each other) and the rate they offer you. If the mid-market rate is 1 CHF = 95 INR, a typical Swiss bank might offer you 91 INR. On a 5,000 CHF transfer, that is a loss of 20,000 INR before you even count the flat fees.
The Swiss Franc remains a powerhouse safe-haven currency. When you send money to India, you are moving money from one of the most stable currencies into one that can be more volatile. Because of this, many banks "pad" their rates even further to protect themselves against intraday fluctuations. Using a transparent service like Wise ensures you get the real mid-market rate, which is the gold standard for saving money on these transactions.
Why Local Swiss Banks Are Often the Worst Choice
Traditional institutions like UBS, Zürcher Kantonalbank (ZKB), or even PostFinance: The Best Option if Traditional Banks Reject You, are built for security and local wealth management, not for high-frequency, low-cost international remittances. They often use the SWIFT network, which involves "intermediary banks."
Each of these intermediary banks can take a small "bite" out of your transfer. By the time your money reaches your HDFC or ICICI account in India, it might be 30 CHF lighter than you expected, and your bank in Switzerland will tell you they have no control over what the other banks charged. This lack of transparency is the primary frustration for Indians living in Zurich, Geneva, or Basel.
Top Strategies for the Cheapest Money Transfers
To find the cheapest way to move money, you need to look outside the mahogany-walled banks of Paradeplatz. The "fintech" revolution in Switzerland has been a godsend for expats. We now have access to digital-first tools that offer transparency that was unimaginable a decade ago.
When you are trying to balance your budget against the Cost of Living in Switzerland 2026: Budgeting for Singles and Families, finding a way to save 100 CHF a month on transfers is equivalent to a small pay raise. It allows you to put more toward your NRE/NRO accounts or pay off a mortgage back home faster.
Using Specialized Online Platforms
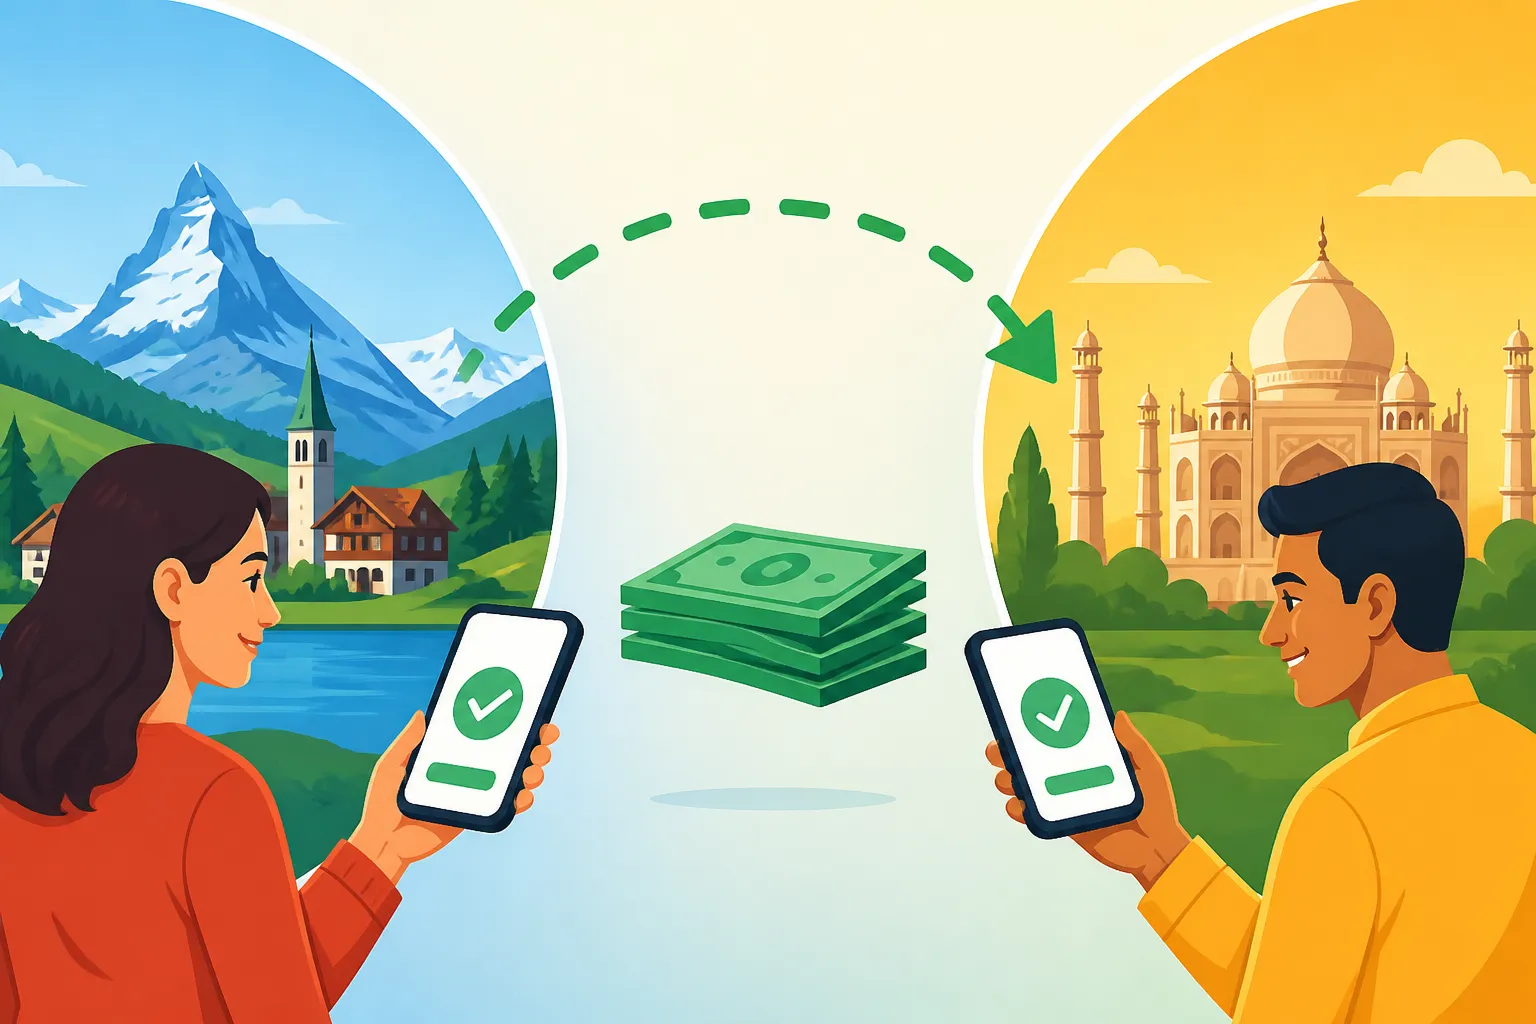
Digital money transfer operators (MTOs) have disrupted the market by cutting out the middleman. Companies like Wise have localized bank accounts in both Switzerland and India. When you "send" money, you are actually just doing a local transfer in Switzerland to their CHF account, and they pay out of their local INR account in India.
This bypasses the SWIFT network entirely, meaning no intermediary fees and near-instant delivery. Because Wise is transparent about their fees and uses the real exchange rate, they are consistently the hero for expats sending anything from 100 CHF to 10,000 CHF. I personally use them for my monthly family support transfers because the app is intuitive and the speed is usually under 24 hours.
Neobanks and Fintech Disruptors
If you have moved your daily banking to one of the Best Neobanks in Switzerland: Neon, Yuh, and Zak Compared, you already know how much cheaper they are for local use. Some of these neobanks have integrated international transfer features directly into their apps.
For example, Neon uses Wise's infrastructure for its international transfers. This means you get the best of both worlds: the security of a Swiss-regulated bank account and the low-cost exchange rates of a specialist provider. While some expats prefer a standalone app for their remittances, having it integrated into your main bank account can save you time and make it easier to track your outgoing wealth for tax purposes.
Managing Large Transfers for Property or Investments
If you are sending a significant sum—say 50,000 CHF or more—to buy a flat in Bangalore or invest in an Indian startup, the strategy changes slightly. While Wise is still great, you might want to look at dedicated currency brokers who can offer "limit orders." This allows you to set a target exchange rate, and the transfer only triggers when the market hits that number.
For these larger sums, you also need to be very aware of documentation. The Swiss authorities and the Reserve Bank of India (RBI) both monitor large cross-border movements. This is where your overall financial health and tax compliance come into play. Keeping a clean record of your Swiss Taxes Explained: Federal, Cantonal, and Municipal Rates is essential because you may be asked to prove the source of funds (your Swiss salary) when the money lands in India.
Cost Comparison: Swiss Banks vs. Digital Providers
To give you a clearer picture, let's look at a hypothetical scenario. Imagine you are sending 2,000 CHF from your account in Switzerland to your family in India. Here is how the costs roughly break down in the current market.
| Provider Type | Estimated Transfer Fee | Exchange Rate Markup | Total Cost (Estimated) | Time to Arrive |
|---|---|---|---|---|
| Traditional Swiss Bank | 25 CHF – 40 CHF | 3% – 5% | 85 CHF – 140 CHF | 3-5 Business Days |
| Wise | 9 CHF – 12 CHF | 0% (Mid-market) | 9 CHF – 12 CHF | Instant to 24 Hours |
| Swiss Neobank (e.g., Neon) | Included or Low | ~0.8% – 1.5% | 16 CHF – 30 CHF | 1-2 Business Days |
| Western Union (Cash) | Variable | High | 50 CHF – 90 CHF | Minutes |
As you can see, the difference is staggering. If you send money once a month, switching from a traditional bank to Wise could save you over 1,000 CHF a year. That’s enough to cover a nice weekend trip to the mountains or a significant portion of your annual health insurance premium.
Understanding Your Account Options in India
As an NRI (Non-Resident Indian) living in Switzerland, you shouldn't just be sending money to a random savings account. To maximize your financial efficiency, you need to understand the NRE (Non-Resident External) and NRO (Non-Resident Ordinary) account structures.
Sending money to the wrong account can lead to tax complications both in India and Switzerland. If you are ever unsure about the international tax implications of your holdings, consulting a specialist like Taxes for Expats can save you from a very expensive audit. They understand the intersection of Swiss wealth taxes and Indian income reporting.
NRE vs. NRO Accounts for Swiss Residents
The NRE account is where most of your Swiss-earned CHF should go. It is a "tax-free" account in India, meaning the interest you earn on your savings is not taxable by the Indian government. More importantly, the funds in an NRE account are fully repatriable. If you decide to move back to Switzerland or another country, you can move that money back out of India without restriction.
The NRO account is generally used for income generated within India, such as rental income from a property you own in Delhi or dividends from Indian stocks. Unlike the NRE, interest earned here is subject to Indian tax. When sending money from Switzerland, always aim for your NRE account to maintain maximum flexibility.
The Role of the Indian IFSC Code and Swiss IBAN
Every time you initiate a transfer, you will need the recipient's IFSC (Indian Financial System Code). This 11-character code is vital for ensuring the money reaches the specific branch of the bank in India. On the Swiss side, you will be dealing with your IBAN.
One common mistake I see new expats make is forgetting to include the reason for the transfer in the "reference" field. For Indian banks, marking it as "Family Maintenance" or "Transfer to NRE Account" can help speed up the internal compliance checks on the receiving end. If you are on a Withholding Tax (Quellensteuer) vs Standard Taxation for Foreigners regime, your employer already reports your income, so having a clear trail of where that money goes is always a good idea for your records.
Tax Implications and Compliance
Don't let the "cheap" part of sending money distract you from the "legal" part. Switzerland has a wealth tax, which means you are taxed on your global assets, including those held in India. If you send 100,000 CHF home and buy a property, that property's value must be declared on your Swiss tax return.
Using a service like Taxes for Expats can be incredibly helpful here. They can help you navigate the Double Taxation Avoidance Agreement (DTAA) between Switzerland and India. You don't want to be in a situation where you are paying tax on the same income in both jurisdictions.
Declaring Outbound Transfers on Your Swiss Tax Return
Many expats believe that once the money leaves Switzerland, it is "gone" from the Swiss tax office's sight. This is a myth. Switzerland participates in the Automatic Exchange of Information (AEOI). This means the Indian tax authorities share data with the Swiss Federal Tax Administration.
If you are sending significant portions of your Understanding Swiss Payslips: Deductions for AHV, ALV, and NBU earnings to India, ensure your Swiss tax return accurately reflects your bank balances in India. Transparency is always cheaper than a penalty. Using Wise for these transfers is helpful because they provide clear, downloadable statements that you can hand over to your tax advisor at the end of the year.
India’s Liberalised Remittance Scheme and FEMA
While the LRS primarily governs money moving out of India, the Foreign Exchange Management Act (FEMA) governs money moving in. As long as you are sending money earned legally in Switzerland, you are generally in the clear. However, if you are a Swiss resident but still have a "resident" savings account in India (instead of converting it to an NRO/NRE), you might be in technical violation of FEMA.
Before you start sending large sums, take a trip back home and convert your accounts. It's one of those administrative hurdles that feels like a pain but prevents massive headaches later. Taxes for Expats can often provide guidance on how these different residency statuses affect your global filing requirements.
Step-by-Step Guide to Your First Transfer
If you're ready to make the switch from your expensive bank to a cheaper digital alternative, here is exactly how to do it. It usually takes less than 15 minutes to set up, and once it's done, you can repeat it with two taps on your phone.
Setting Up Your Wise Account in Switzerland
- Download the app: It’s available on the Swiss App Store.
- Register with a Swiss address: Use your residence permit (B or L permit) address.
- Set up the transfer: Choose CHF as the source currency and INR as the target.
- Enter recipient details: You will need the recipient's full name (as it appears on their bank account) and their IFSC code.
- Choose your payment method: You can pay via a local Swiss bank transfer (using your e-banking) or via a debit/credit card. Note: A bank transfer from your Swiss account to Wise’s Swiss account is usually the cheapest way.
Verifying Your Identity and Address
Because of Switzerland's strict Anti-Money Laundering (AML) laws, you will need to verify your identity. Usually, a quick photo of your Swiss B-Permit or your passport will suffice. Wise is very fast with this; I've seen accounts verified in under two hours.
Once verified, you are ready to send. The app will show you exactly how much the recipient will get in INR, the exact exchange rate being used, and the exact date the money will arrive. No "intermediary bank" surprises. This level of control is why most of us in the Indian expat community have moved away from traditional banks entirely.
Disclaimer
This guide is for informational purposes only and does not constitute financial, legal, or tax advice. Exchange rates and fees are subject to market volatility and provider policy changes. While we strive for accuracy, please verify all rates and compliance requirements with your chosen provider and a qualified tax professional before committing to large financial transactions. Specific tax situations, especially for those with complex global assets, should be reviewed by specialists such as Taxes for Expats to ensure full compliance with both Swiss and Indian regulations.